Most money stress doesn’t come from one big disaster. It builds slowly, out of small worries that never quite go away. It follows people into the grocery store, keeps them up at night and colors conversations at home. Often the cause isn’t a particular bill at all. It’s the feeling of having no room for error, where any change in circumstances could tip things over.
An emergency fund is one of the simplest ways to ease that feeling. It won’t make you rich, and it won’t fix spending that outpaces income. What it does is give you breathing room. Problems that once felt frightening become problems you can plan around. The sections below look at why that breathing room matters so much, how to build it at a steady pace, and where to keep it so the money grows while it waits.
Why Does Money Worry Feel So Heavy?
Uncertainty Is the Real Weight
You can have enough money for this month’s bills and still feel anxious. That’s because the worry usually isn’t about today. It’s about tomorrow, and whether you could handle something going wrong. As long as that question stays open, your mind keeps returning to it.
Plenty of people live with this feeling. The Federal Reserve’s yearly Survey of Household Economics and Decisionmaking has found again and again that many adults couldn’t cover a modest surprise expense with cash. For them, a dead car battery or a surprise vet bill means choosing which other payment has to wait.
One Problem Becomes Several
Without savings, a single expense rarely stays single. The repair goes on a credit card, and the higher balance raises the minimum payment. That payment eats into next month’s grocery money, so more spending lands on the card. What started as one bad afternoon can turn into months of catching up. The stress grows right along with the balance.
An emergency fund breaks that cycle early, before one problem has a chance to turn into several.
What Changes Once You Have a Cushion?
You Get to Slow Down
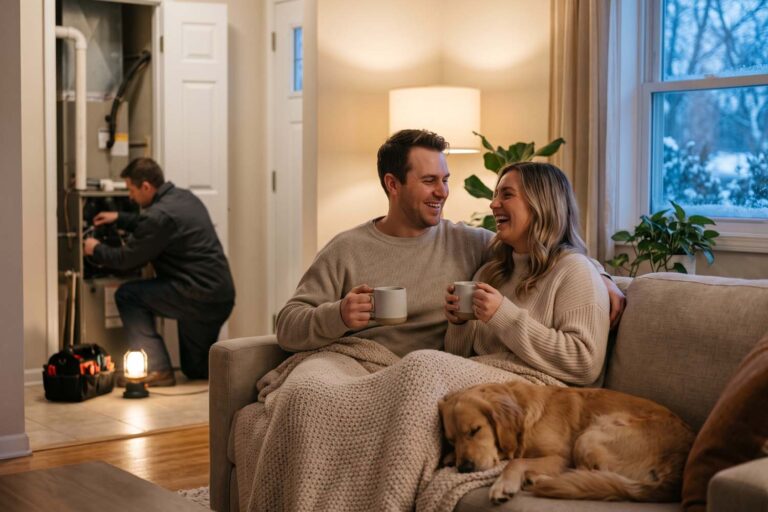
Having cash set aside means you don’t have to make every decision in a rush. When the furnace stops working, you can call two or three repair companies and compare quotes. When your laptop breaks, you can take a day to find a fair price instead of grabbing the first option. This kind of patience saves money, but it also saves you from the panic of deciding under pressure.
Your Attention Comes Back
When money is tight, it takes up a lot of mental space. You keep track of every purchase, run numbers in your head and check your balance more often than you’d like. A cushion lets you set some of that down. You can think about next year instead of next week, focus better at work and enjoy a meal out without doing math at the table. Your other goals stay safe, too, since you won’t need to pause retirement savings or miss a debt payment to cover a surprise.
Those benefits are clear enough. The harder part is building the fund when the budget already feels stretched.
Money stress often comes less from how much you have and more from how unprotected you feel.
How Do You Build One Without Feeling Squeezed?
Begin Smaller Than You Think
You’ve probably heard that an emergency fund should hold three to six months of essential expenses. That’s a sensible long-term goal, but it can feel so far off that starting seems pointless. A smaller first target works better. Try saving $500, or about one month’s rent, and celebrate when you reach it. An early win makes the habit feel real, and the larger goal starts to look possible.
Let the Saving Happen on Its Own
Saving is easier when you don’t have to think about it. Set up an automatic transfer on payday so the money moves before you have a chance to spend it. Even $25 a week becomes $1,300 in a year without much effort. If you want a simple plan to follow, the Consumer Financial Protection Bureau’s guide to building an emergency fund covers how to set a goal and make saving automatic.
It also helps to decide ahead of time what counts as an emergency. A good rule is that the cost should be unexpected, necessary and urgent. A hospital bill fits all three. A great deal on a new TV doesn’t. Settling this early keeps the fund from slowly drifting into everyday spending.
As your balance starts to grow, it’s worth thinking about where that money should live.
Where Should the Money Live?
A High-Yield Savings Account Strikes the Right Balance
Your emergency fund needs to be easy to reach in a real emergency but not so handy that you tap it on impulse. A separate high-yield savings account, often offered by online banks, does this well. Moving money to your checking account usually takes a day or two. That small delay gives you a moment to think before spending, but it’s short enough that you’re never stuck when you truly need the cash.
Your Savings Can Earn More
Standard savings accounts at many large banks pay very little interest. High-yield accounts often pay much more, and on a growing balance that difference adds up. For example, $5,000 earning 4% APY would make about $200 in a year, while the same amount at 0.01% would earn around 50 cents. Rates go up and down over time, so shopping around is worth the effort. Comparing the top savings account rates before you open an account can help you find a bank that pays well, since rates differ more from bank to bank than many people realize.
That extra interest also helps your savings keep up with rising prices. The cushion you build today stays strong enough to cover a similar emergency a few years down the road.
Make Sure Your Money Is Protected
A calm fund should also be a safe one. Before you choose a bank, check that it’s insured. With FDIC deposit insurance, deposits at member banks are covered up to $250,000 per depositor, per insured bank, for each ownership category. Credit unions offer similar protection through the NCUA. For nearly every emergency fund, that means your money is secure even if the bank runs into trouble.
It’s also smart to read the account terms closely. Look for monthly fees, minimum balance requirements, withdrawal limits and how long transfers take. Most rates are variable, so today’s number can change later. An account with a slightly lower rate and no fees is often the better choice.
Once the fund is in place, keeping it healthy takes only a little ongoing care.
How Do You Keep the Calm Going?
Refill It After You Use It
Spending from your emergency fund doesn’t mean you did something wrong. That’s exactly why it exists. The important step is restarting your automatic transfers right away, and maybe increasing them for a little while, so the fund is ready again before the next surprise comes along.
Check In Once a Year
Life changes, and your fund should change with it. A new baby, a move, a raise in rent or a job with less steady pay can all shift what a few months of expenses really means. Take a look at your target once a year, or after any major change, and adjust it so it still fits the life you’re living.
The Bottom Line
Money stress often comes less from how much you have and more from how unprotected you feel. An emergency fund narrows that gap. It gives you time to make good choices, frees up mental energy and stops one hard moment from spilling into the months ahead. Building it gradually, keeping it somewhere safe that earns interest and refilling it after each use turns it into a steady source of security. The point isn’t to expect the worst. It’s to know you’ll be able to handle whatever comes with a clear head.

Better Living may earn commissions through affiliate links and may occasionally feature sponsored or partner content. If you make a purchase through our links, we may receive a small commission at no cost to you.